Homeowners Insurance Discounts: Bundling, Security Systems, and Other Ways to Save
Beginning with Homeowners Insurance Discounts: Bundling, Security Systems, and Other Ways to Save, the narrative unfolds in a compelling and distinctive manner, drawing readers into a story that promises to be both engaging and uniquely memorable.
Exploring the various ways homeowners can save on insurance through bundling, security systems, and other methods sets the stage for a comprehensive understanding of maximizing savings in this crucial area.
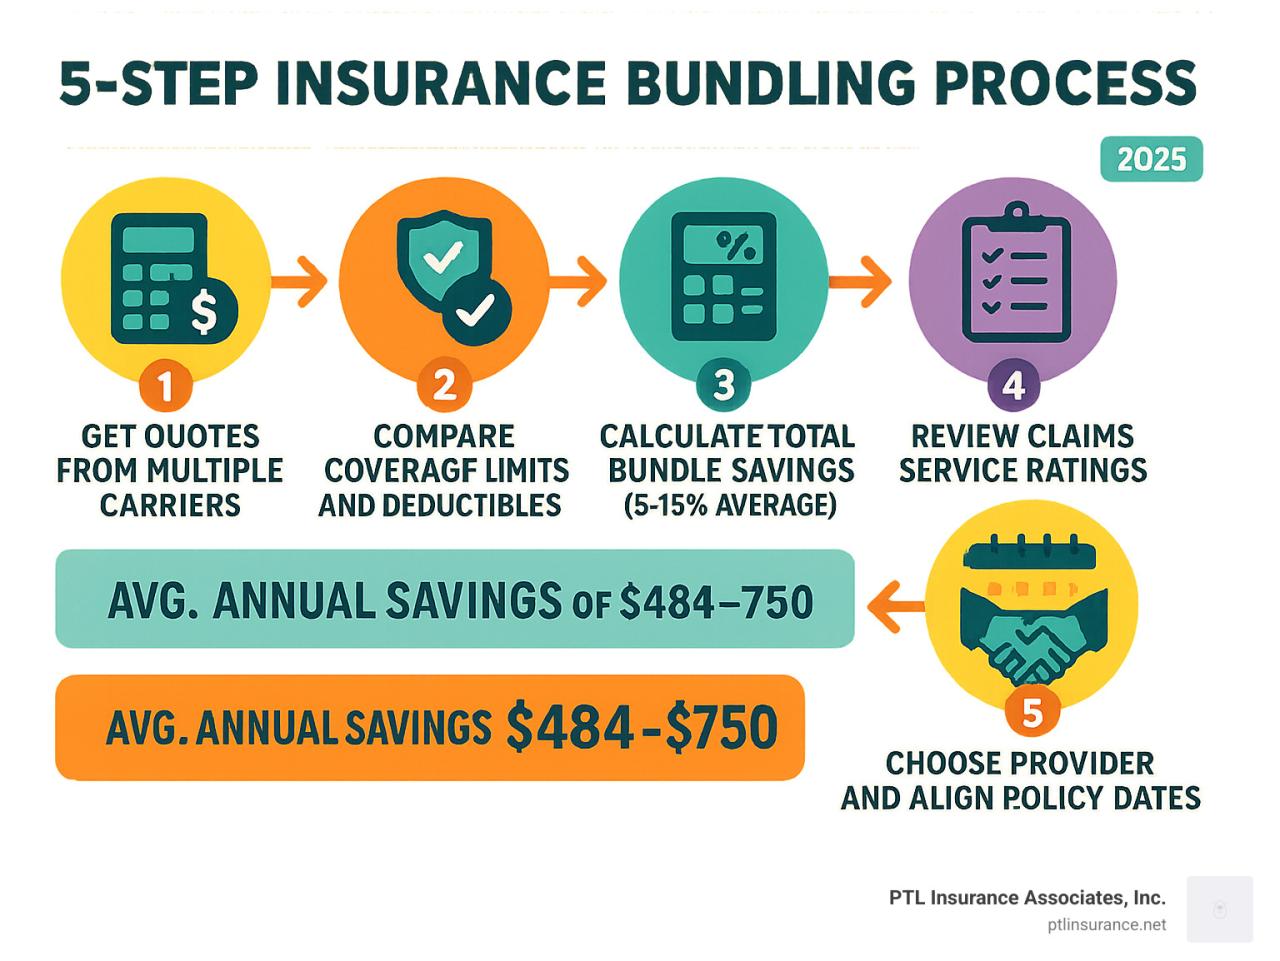
When it comes to homeowners insurance, bundling can be a great way to save money on your premiums. By combining your homeowners insurance policy with other types of insurance such as auto or life insurance, insurance companies often offer discounts as an incentive to keep all your policies with them.
When you bundle your homeowners insurance with other policies, you not only save money on each individual policy but also benefit from the convenience of having all your insurance needs met by one provider. This can result in overall cost savings and a streamlined insurance experience for homeowners.
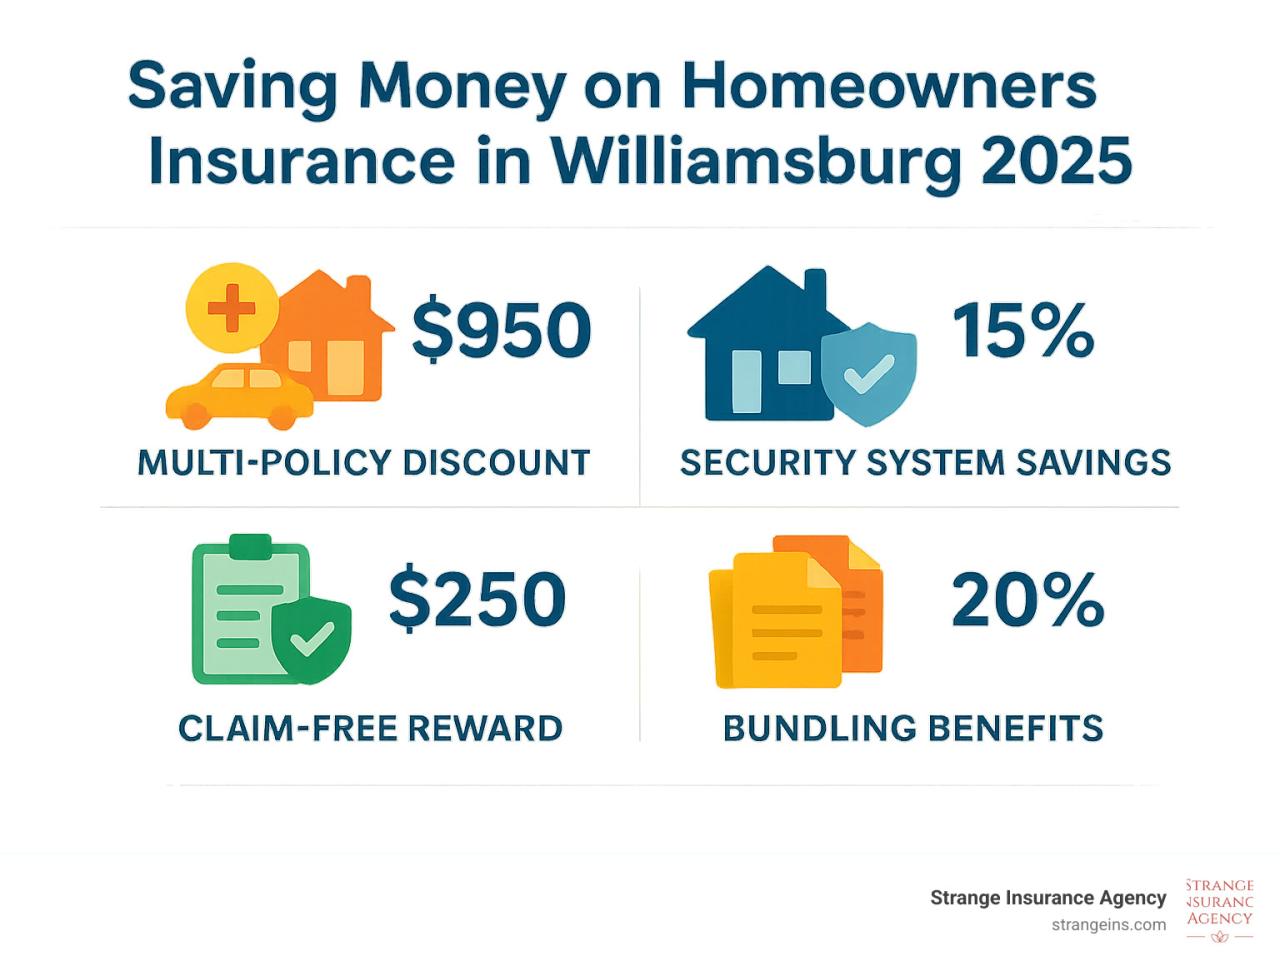
Installing a security system in your home can lead to significant discounts on your homeowners insurance premiums. Insurance companies view security systems as a way to reduce the risk of break-ins, theft, and other potential damages, ultimately resulting in lower claims and costs for them.
According to a study by the Insurance Information Institute, homes with security systems are 20% less likely to be burglarized than those without, significantly reducing the risk of theft-related insurance claims.
Furthermore, the presence of a security system can also lead to quicker response times from emergency services, minimizing potential damages and losses in the event of a break-in or other security breach.
When it comes to saving on homeowners insurance, there are several lesser-known methods that can help reduce your premiums. Factors such as location, home age, and construction materials can all impact insurance costs. Additionally, improving your credit score can also lead to lower insurance rates.
Location plays a significant role in determining homeowners insurance premiums. Homes located in areas prone to natural disasters such as hurricanes, earthquakes, or floods may have higher insurance costs due to increased risk. Conversely, homes in low-crime neighborhoods or areas with good access to fire departments may qualify for lower premiums.
The age of your home and the materials used in its construction can also affect insurance rates. Older homes may have outdated electrical systems or plumbing, increasing the risk of damage and potential insurance claims. Similarly, homes constructed with fire-resistant materials like brick or metal may be eligible for discounts on insurance premiums.
Insurance companies often use credit scores as a factor in determining homeowners insurance rates. By improving your credit score through timely bill payments, reducing debt, and monitoring your credit report for errors, you can potentially qualify for lower insurance premiums.
A higher credit score demonstrates financial responsibility and reduces the perceived risk for insurers.
Can I bundle homeowners insurance with other policies to get discounts?
Yes, bundling homeowners insurance with policies like auto or life insurance often leads to discounts from insurance providers.
Do security systems really help in lowering homeowners insurance premiums?
Having a security system installed can indeed lower insurance premiums as it reduces the risk of home insurance claims.
Are there other lesser-known ways to save on homeowners insurance?
Yes, factors like location, home age, and construction materials can impact insurance costs, and improving your credit score can also help qualify for lower rates.
